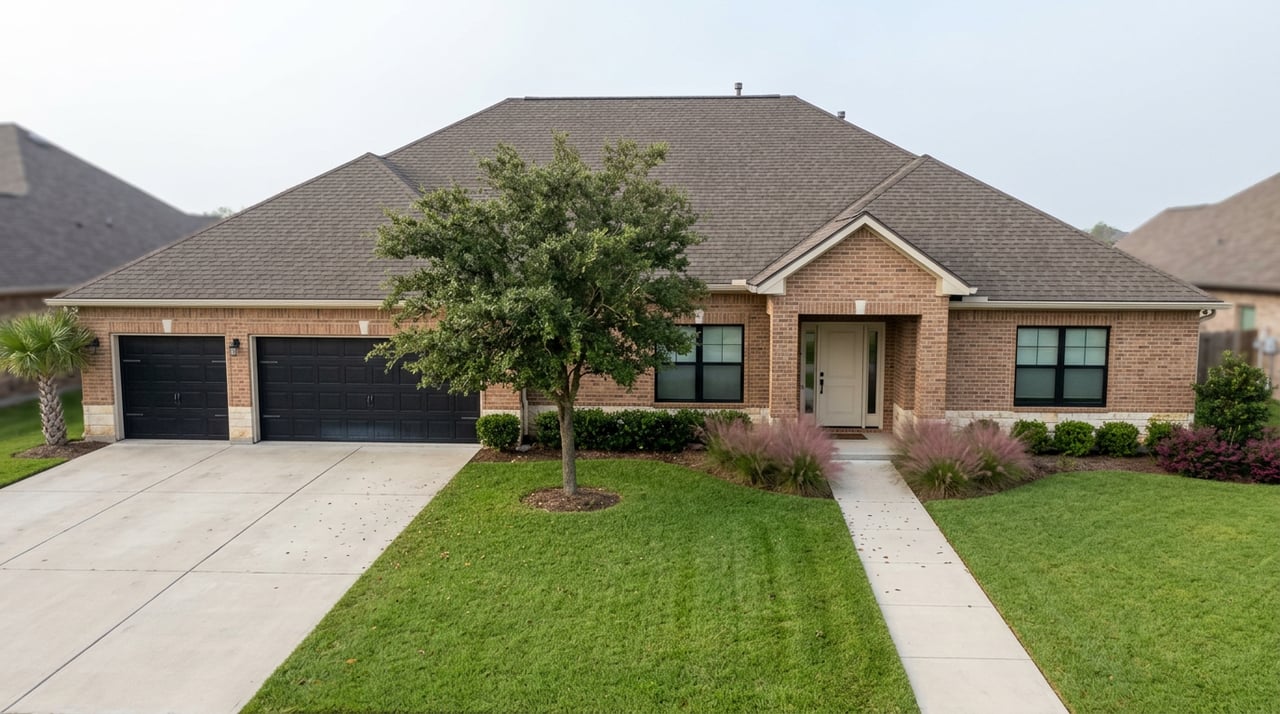
A buyer went under contract on a new-construction home in one of Milton's developments south of I-10 this year. Across the street, the identical floor plan had just closed for $330,000. He closed for $289,000. The builder threw in every appliance, bought his VA rate down to just under 4 percent, and handed back his $1,000 earnest money at the closing table. Same builder. Same model. Same month. A $41,000 spread on paper, and he walked in with nothing out of pocket.
That gap has nothing to do with who negotiated harder. It happened because in Milton right now, the number printed on a listing and the number that actually changes hands are only loosely related to each other. If you've searched "Milton FL home prices" and come away more confused than when you started, that's not a research failure on your part. It's what the market is actually doing.
The List Price Is an Opening Position, Not a Settled Number
Milton had 84 active listings against 11 homes under contract in a recent read of live MLS data, a pending-to-active ratio of about 0.13. That ratio matters more than any single price point, because it tells you who holds the leverage in a negotiation. With that much unsold inventory sitting against so few pending deals, sellers are competing for buyers, not the other way around.
The price gap shows it plainly. The median asking price across those active listings ran $333,634, while the median closed sale over the trailing six months came in at $304,831. That's not a rounding difference. It's nearly $29,000 of daylight between what sellers hope for and what buyers actually pay, built on 654 recorded closings, enough volume to treat as a pattern rather than noise. The middle half of those closings landed between $244,900 and $378,082, which is the range worth writing offers against, not the asking price on whatever listing caught your eye.
If you're pricing an offer off what a home is asking, you're negotiating against a number a good portion of Milton's own sellers have already had to walk back.
Milton's "Median Price" Depends on Which Zip You Ask
Ask five different sources for Milton's median home price and you'll get five different answers, and the reason isn't sloppy data. It's that "Milton" isn't one price tier. Zip 32583 showed a typical home value of $292,483 as of early August 2026, with a cap rate near 8.2 percent, an unusually strong number for rental yield in this part of the Panhandle. Zip 32570, pulled about a month earlier, showed $278,393 and a softer 7.62 percent cap rate. Same city, same season, two zip codes reading almost $15,000 apart on value and more than half a point apart on yield.
Layer in a citywide read from earlier in the spring that put the median sale at $320,000, and you can see how three honest, current numbers can all be true at once and still look like they contradict each other.
| Source | Figure | Data Vintage |
|---|---|---|
| Zillow Home Value Index | $288,286 average home value | July 31, 2026 |
| Live MLS read (Resideline) | $304,831 median sold vs. $333,634 median ask | July 2026 |
| Zip 32583 typical value | $292,483 | August 1, 2026 |
| Zip 32570 typical value | $278,393 | July 6, 2026 |
| Earlier-year citywide read | $320,000 median sale | April 2026 |
None of these numbers is wrong. They're measuring different slices of the same town at different moments. The practical takeaway is that a Milton median price only means something once you know which zip code, which price tier, and which month it was pulled from.
The Subdivisions Behind the Number
Zoom past the zip codes and the picture gets more useful. Momentum's new-construction tracking counted roughly 152 active new-build homes spread across 16 Milton communities, priced from about $160,000 to $974,899. A broader national listing count put Milton's new-home inventory at 688 homes across 80 communities and 25 builders, ranging from $180,990 to $1,699,900. That's not a starter-home town with a ceiling. It's a town with several different price tiers stacked on top of each other, and the subdivision name tells you more than the citywide median ever will.
Las Colinas is marketed on lake-view homesites inside an already-established neighborhood, a rarer setup than the typical greenfield subdivision. Blackwater Reserve sits minutes from downtown and the river. Yellow River Ranch spans roughly 1,400 acres as a master-planned community built around preserving the tree cover rather than clearing it. Thomas Homes is building brick houses on one-acre lots with three-car garages at Nichols Creek. Holiday Builders is putting up 300 homesites between Milton and Pace at Whisper Creek. Gulf Coast Dream Homes has four-bedroom houses tucked into scrub oak and pine at Eventide Estates, off Trout Bayou near the Garcon Point Estuary. Horizon's Edge is the newest of the group, cottage-style homes aimed at a different buyer than the acreage lots further out.
D.R. Horton is building the largest share of that inventory, which matters for the next part of the story.
Incentives Do the Work Sticker Price Cuts Used to Do
Builders with this much active inventory rarely cut the sticker price. Cutting price resets the appraisal comp for every other house they're still trying to sell in the same subdivision. What they will do is stack incentives on top of the existing price: a rate buydown, free upgrades, closing cost credits, appliances already installed. That's exactly what happened to the buyer in the opening story. His $289,000 closing price wasn't a discount the builder advertised. It was the sticker price plus a $50,000 incentive package layered underneath, which is a very different negotiation than asking a seller to simply come down on price.
If you're cross-shopping new construction in Milton, the question worth asking isn't "what's your best price." It's "what's the full incentive stack you're running this month," because that number moves far more than the price on the sign does.
The BAH Math That Makes Milton's Spread Matter
Milton sits inside the Pensacola military housing area, designated FL064, the same allowance zone that covers NAS Whiting Field. For 2026, the monthly Basic Allowance for Housing with dependents runs about $1,863 for an E-5, $2,235 for an E-6, and $2,271 for an O-3. An E-5's BAH comfortably supports a mortgage in the $275,000 to $320,000 range in Milton, which lines up almost exactly with the sold-price range this piece has been walking through. That same allowance stretches considerably less in Gulf Breeze, where the price tier runs well above Milton's, or even in Pace, where newer subdivisions carry a modestly higher price point.
That's the part the citywide median hides. A buyer using BAH to qualify isn't shopping "Milton's median price." They're shopping the specific band where their allowance and a builder's incentive stack actually meet, and Milton is one of the few towns in this housing area where that band lines up cleanly with move-in-ready inventory.
The Town Isn't Standing Still While You Compare Numbers
None of this pricing confusion has slowed Milton's growth. Jack's Family Restaurants opened its first Florida location anywhere at 6625 Caroline Street in Milton on March 23, 2026, choosing the town over every other Florida market for its debut in the state. The company's CEO framed the decision around Milton's daily rhythm, a place people would stop into before heading out on the Blackwater River or gathering for dinner after work. A regional chain doesn't pick a town for its first-in-state location on a whim. It picks a town where the rooftop count and the daily traffic already justify the bet.
Before You Write an Offer in Milton
- Pull closed comps for the specific subdivision, not the citywide median. A number from Las Colinas tells you nothing about Nichols Creek.
- Ask what zip code any online estimate is actually built from. A $15,000 gap between 32570 and 32583 is common, not an error.
- On new construction, ask for the full incentive stack before comparing sticker prices between builders.
- If you're buying with BAH, run your specific rank and dependent status against current Milton inventory before you set a budget, since the range that works for an E-5 doesn't automatically work for an E-4.
Milton's price story only looks confusing from a distance. Up close, it's a town where the gap between the asking number and the closing number is real money, and where the right subdivision, the right builder incentive, or the right BAH bracket can put a home within reach that the citywide median made look out of range. If you want a read on what a specific Milton subdivision or price tier looks like for your situation, Michael Tracy can walk through the current inventory and the incentives attached to it. Schedule a free consultation and get numbers built around your actual budget, not a citywide average that doesn't apply to it.